

IATA: Airline industry profits expected to rise slightly in 2025
IATA forecasts a modest increase in airline industry profits in 2025, supported by lower fuel prices. However, the association warns of significant challenges ahead, particularly in air cargo operations and supply chains.
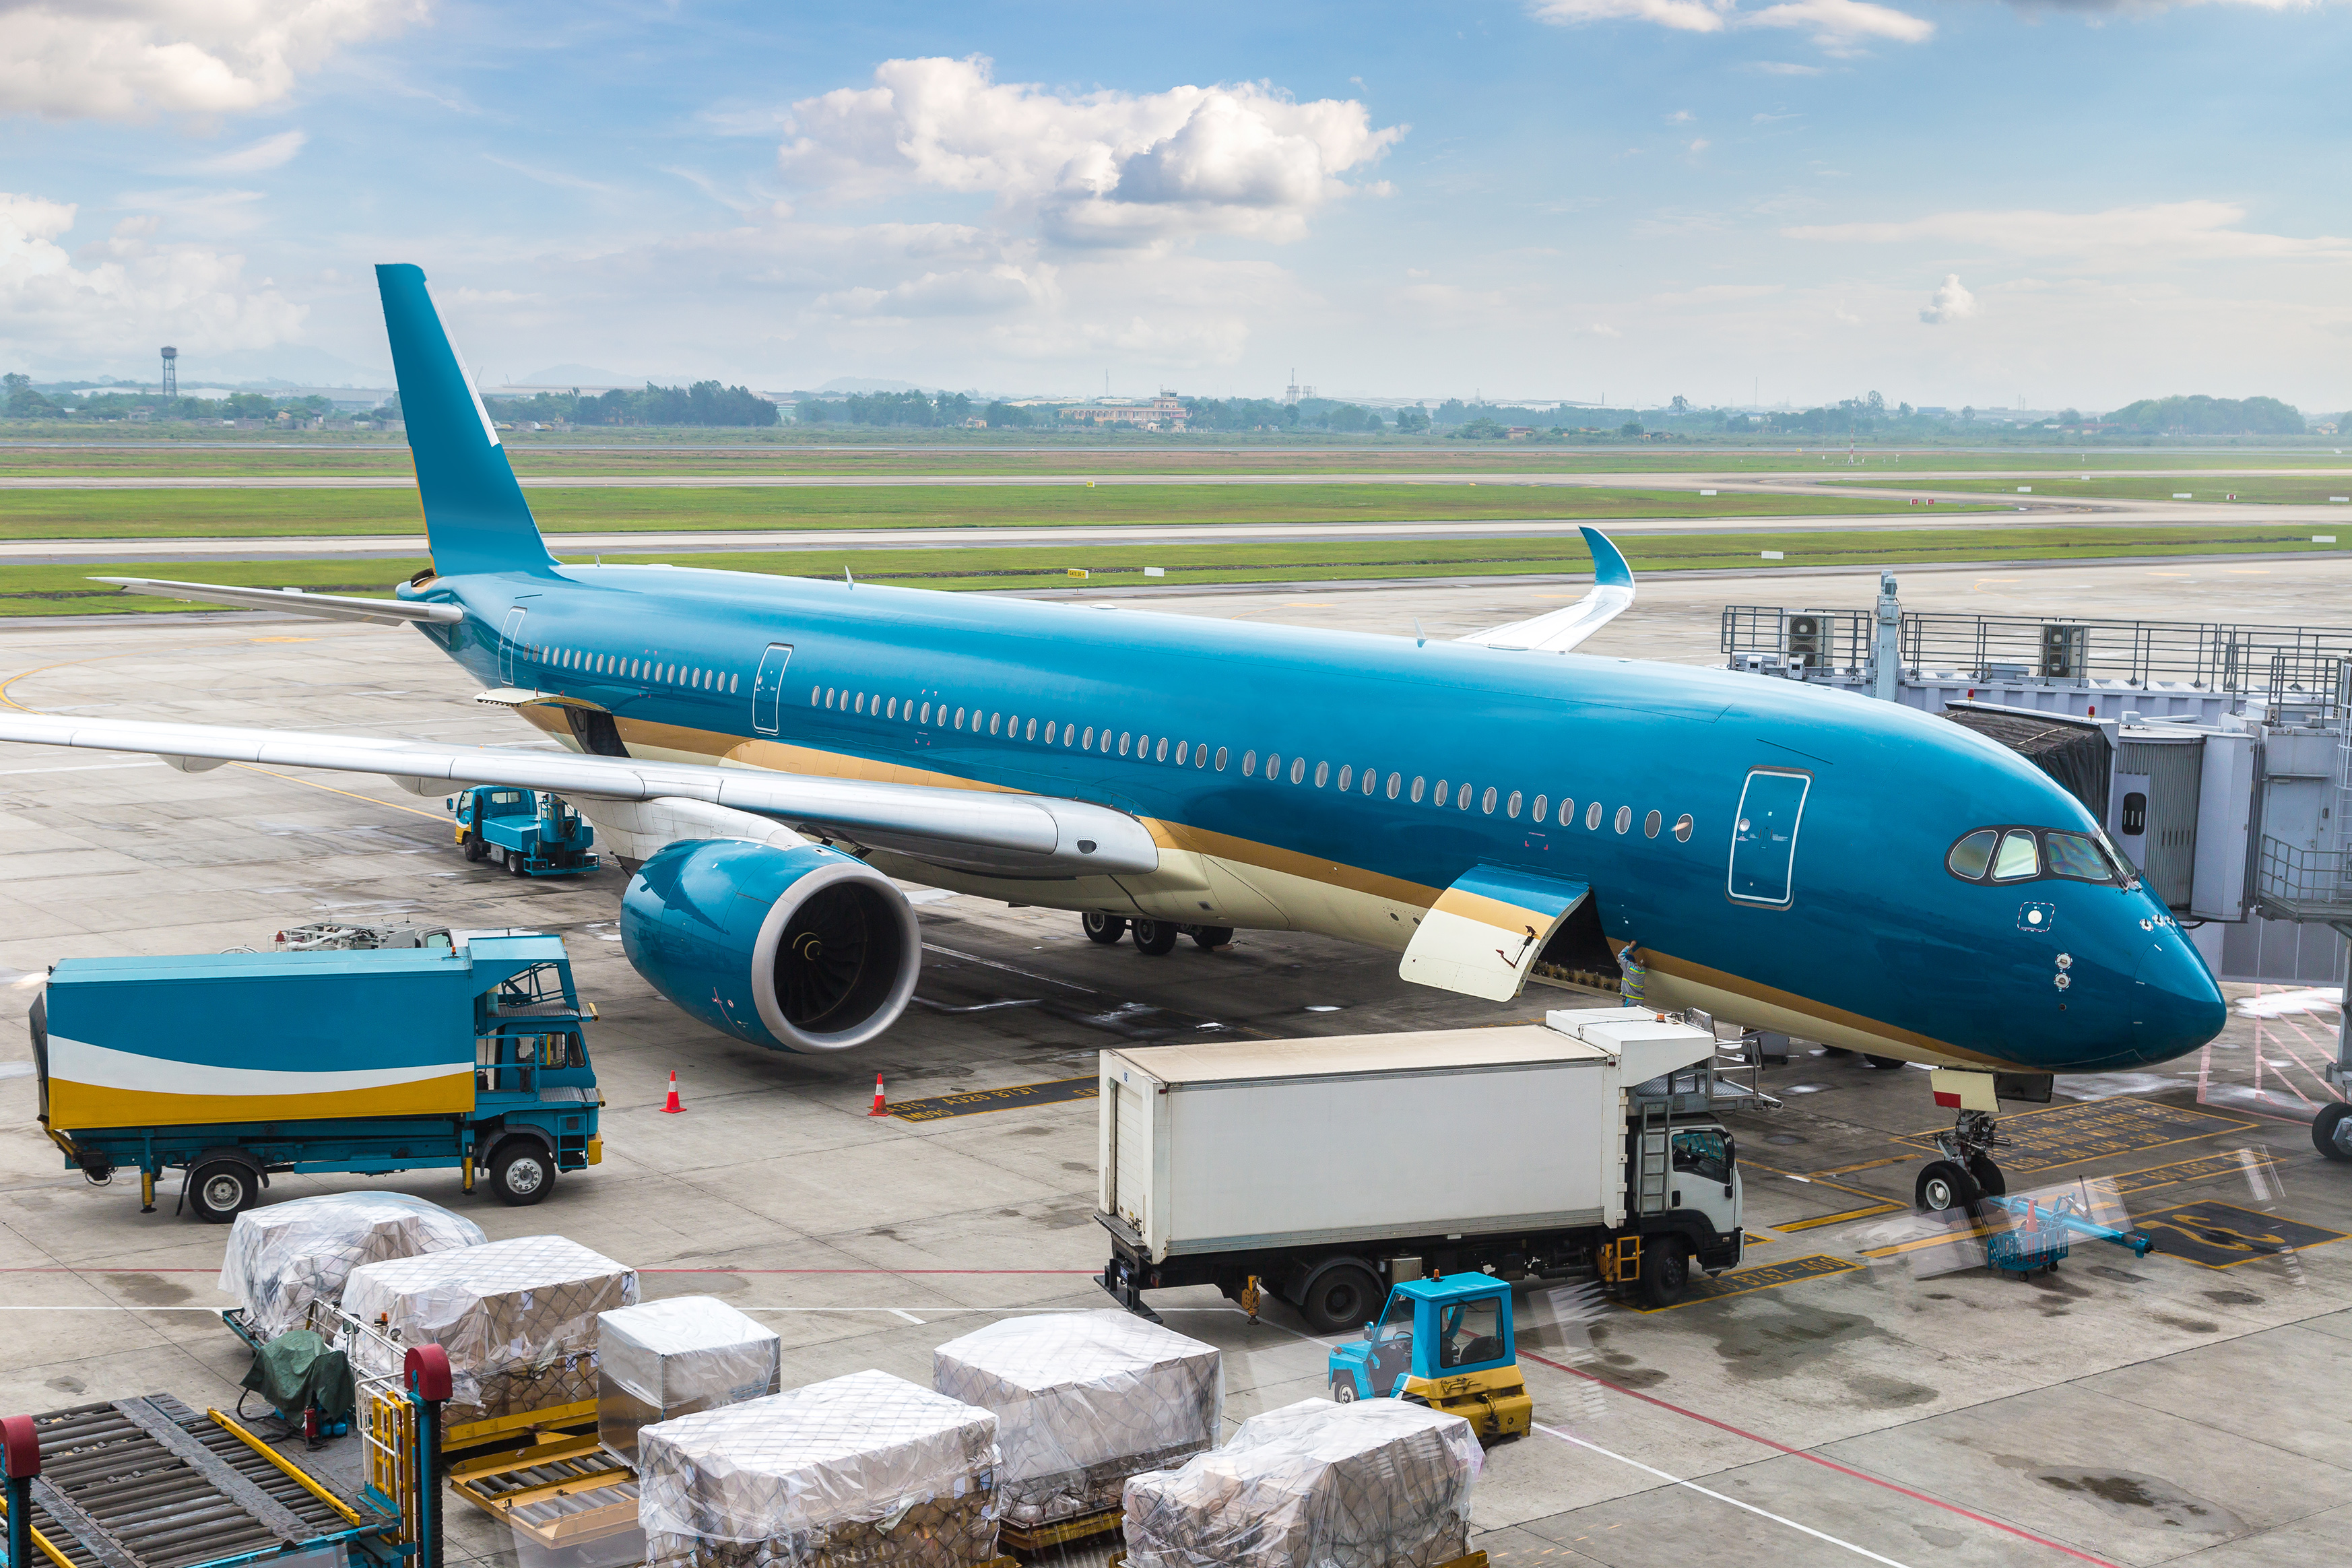
The global airline industry is expected to see a modest improvement in profitability in 2025, despite facing a range of challenges, including trade tensions, prolonged supply chain disruptions, and geopolitical uncertainties.
According to the latest financial outlook from the International Air Transport Association (IATA), the industry's net profit is projected to reach USD 36 billion in 2025, up from USD 32.4 billion recorded in the previous year, although slightly below IATA's earlier forecast of USD 36.6 billion. Passenger revenue is expected to rise to an all-time high of USD 693 billion, representing a 1.6% year-on-year increase. This growth is driven by strong passenger demand and a record passenger load factor of 84%.
This growth is anticipated despite a projected 4% decline in average passenger yields due to lower oil prices and intensifying competition among airlines. Ancillary revenue is also expected to increase by 6.7% to USD 144 billion, bringing total industry revenue to a record USD 979 billion.
IATA Director General Willie Walsh stated: "Despite the headwinds, 2025 is expected to be a better year for airlines. The net profit margin is projected to rise to 3.7%, up from 3.4% in 2024, demonstrating the industry's resilience in the face of economic and political challenges."
According to IATA, the anticipated improvement in profitability is largely attributed to a significant 13% decline in jet fuel prices compared to 2024, with an average price forecast of USD 86 per barrel. This translates into estimated fuel costs of USD 236 billion, accounting for approximately 26% of airlines' total operating expenses, a substantial decrease from USD 261 billion in 2024.
Walsh emphasized that the relief provided by lower fuel prices is crucial for the industry, as airlines' narrow net profit margins—equivalent to just USD 7.20 per passenger—leave the sector particularly vulnerable to sudden shocks involving taxes, regulations, or input costs.
However, the air cargo segment presents a less optimistic outlook, with revenue projected to decline by 4.7% to USD 142 billion. This reflects expectations that global GDP growth will slow from 3.3% in 2024 to 2.5% in 2025. Trade tensions, particularly tariff measures, are expected to constrain air cargo demand growth to just 0.7%, a significant slowdown from the 11.3% growth recorded in 2024. Cargo yields are also forecast to decline by 5.2%, while ongoing supply chain disruptions are expected to remain a major obstacle.
According to IATA, the airline industry is facing an aircraft order backlog exceeding 17,000 units, with waiting times extending up to 14 years. Engine-related issues and parts shortages have resulted in a record number of aircraft under ten years old being grounded, contributing to reduced operational efficiency and higher aircraft leasing costs.
Walsh warned that these delays could persist until the end of the decade. He stated: "Manufacturers continue to disappoint, and there is no indication that these challenges will come to an end anytime soon."
Nevertheless, regional profitability is expected to remain positive across all markets. Middle Eastern airlines are forecast to lead with a net profit margin of 8.7%, while African carriers are expected to lag behind at 1.3%.
Walsh urged policymakers to exercise caution, emphasizing that the aviation industry supports 86.5 million jobs and contributes 3.9% to global economic activity. He noted that any additional costs or regulatory burdens could quickly erode the industry's already fragile profit margins.
Looking ahead, IATA noted that the industry remains focused on balancing growth with sustainability.
Sustainable Aviation Fuel (SAF) production is expected to double to two million tonnes in 2025. However, this volume will still account for less than 1% of the industry's total fuel consumption, highlighting the urgent need to scale up production to meet the net-zero emissions target by 2050.
Source: The Freight News
Share


Head Office
ASL CAMBODIA

No.09C Street 367, Sangkat Chbar Ompov 1, Khan Chbar Ampov, Phnom Penh Capital, Kingdom of Cambodia

+855 31 555 6688

ceo@asl-cam.com

www.aslcambodia.com
LOGISTICS SERVICES
Related News

12/10/2026
Six German ports avert strike threat as Maersk imposes low-water surcharge on Rhine river
07/06/2025
Maersk and Hapag-Lloyd launch new shipping service from China to the United States
31/05/2025
Shippers left in limbo as Trump appeals tariff ruling

ASL Logistics Cambodia
Your True Logistics Partner


